

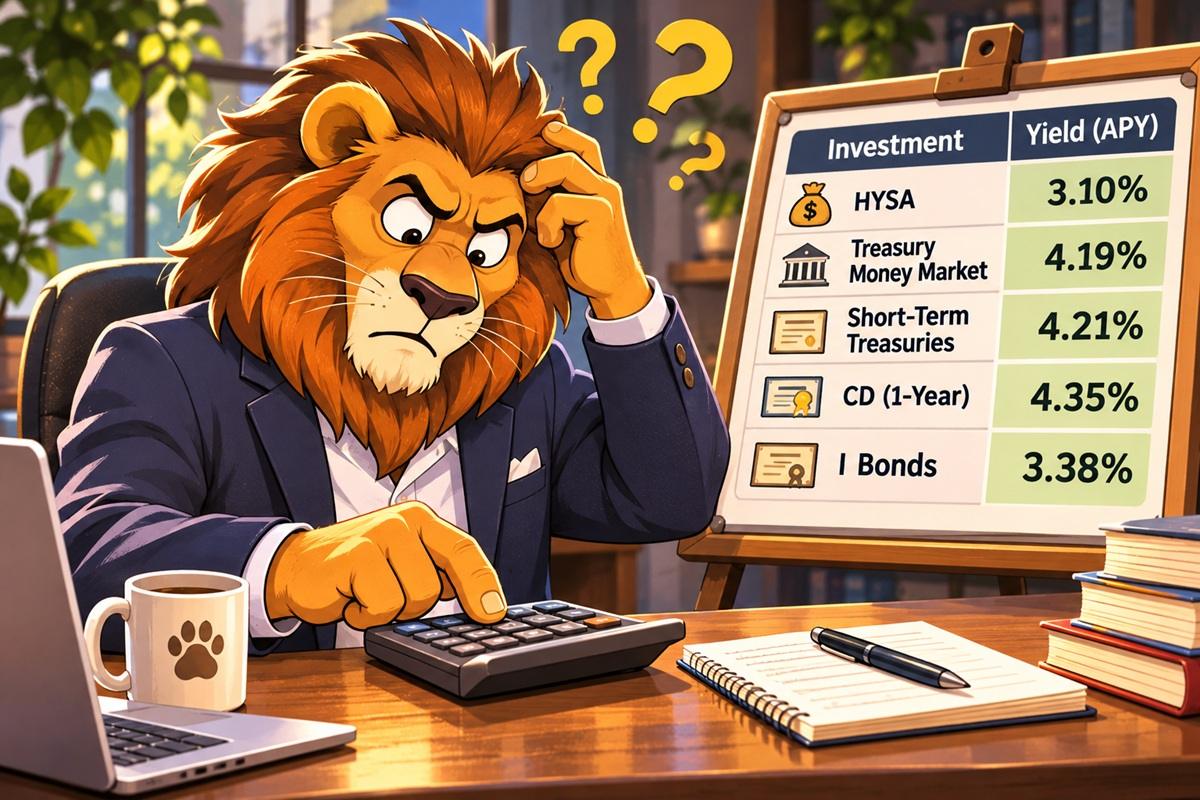
Comparing Savings Options: High-Yield Savings Accounts versus Treasury Money Market Funds
When considering where to best allocate your funds, opting for the account with the most competitive advertised interest rate may not guarantee maximum returns. Understanding the nuances between different savings vehicles is crucial for optimizing your earnings.
High-yield savings accounts (HYSAs) and Treasury money market funds both serve as effective options for parking your cash; however, they differ significantly in terms of tax implications. Depending on your individual tax burden, a Treasury money market fund might yield a higher return after taxes.
Introducing the Tax-Equivalent Yield Calculator
To assist in making informed decisions, our Tax-Equivalent Yield Calculator enables you to evaluate and compare these two financial options based on post-tax earnings.
Utilizing the Calculator
To commence, input the amount you plan to save or invest, along with the interest rate for your high-yield savings account and the yield from a Treasury money market fund.
Subsequently, provide your federal marginal income tax rate, in addition to any combined state and local income tax rates. The tool also allows for modifications to the percentage of the Treasury fund’s income that may qualify for state tax exemptions.
The calculator delivers the following insights:
- After-tax HYSA yield: This reflects the effective annual yield from your savings account after accounting for federal, state, and local taxes.
- After-tax Treasury money market yield: This details the effective annual yield from the Treasury fund once potential state and local tax benefits are considered.
- Tax-equivalent yield: This indicates the yield a fully taxable savings account would need to provide to match the Treasury fund’s after-tax return.
- Annual dollar difference: This reveals the potential annual earnings advantage of one option over the other, based on your investment balance.
This ensures a straightforward comparison of the two options based on after-tax outcomes.
Why Treasury Money Market Funds May Offer a Tax Benefit
Interest accrued in a high-yield savings account is typically subject to federal income tax, in addition to any applicable state and local taxes. Conversely, income generated from U.S. Treasury securities is taxable at the federal level but generally exempt from state and local taxation.
Treasury money market funds invest in short-term Treasury securities and potentially other liquid assets. Depending on the composition of the fund, a portion or all of its distributed income might also qualify for the same state and local tax exemptions.
For instance, consider the following scenario:
- A high-yield savings account with an APY of 4.00%.
- A Treasury money market fund offering a yield of 3.80%.
- A federal marginal tax rate of 24%.
- A combined state and local income tax rate of 8%.
If the income from the Treasury fund is fully exempt from state and local taxes, the estimated after-tax yield from the HYSA would stand at 2.72%, whereas the Treasury fund’s yield would be 2.89%.
Additionally, the Treasury fund’s tax-equivalent yield would be approximately 4.25%, indicating the necessary yield of a taxable savings account to match the Treasury fund’s after-tax return.

Chief Editor of Quincy City Beat — Quincy, MA's independent investigative newspaper covering Greater Boston and the entire Commonwealth of Massachusetts with fearless public accountability and free access for all readers.



Discussion about this post