

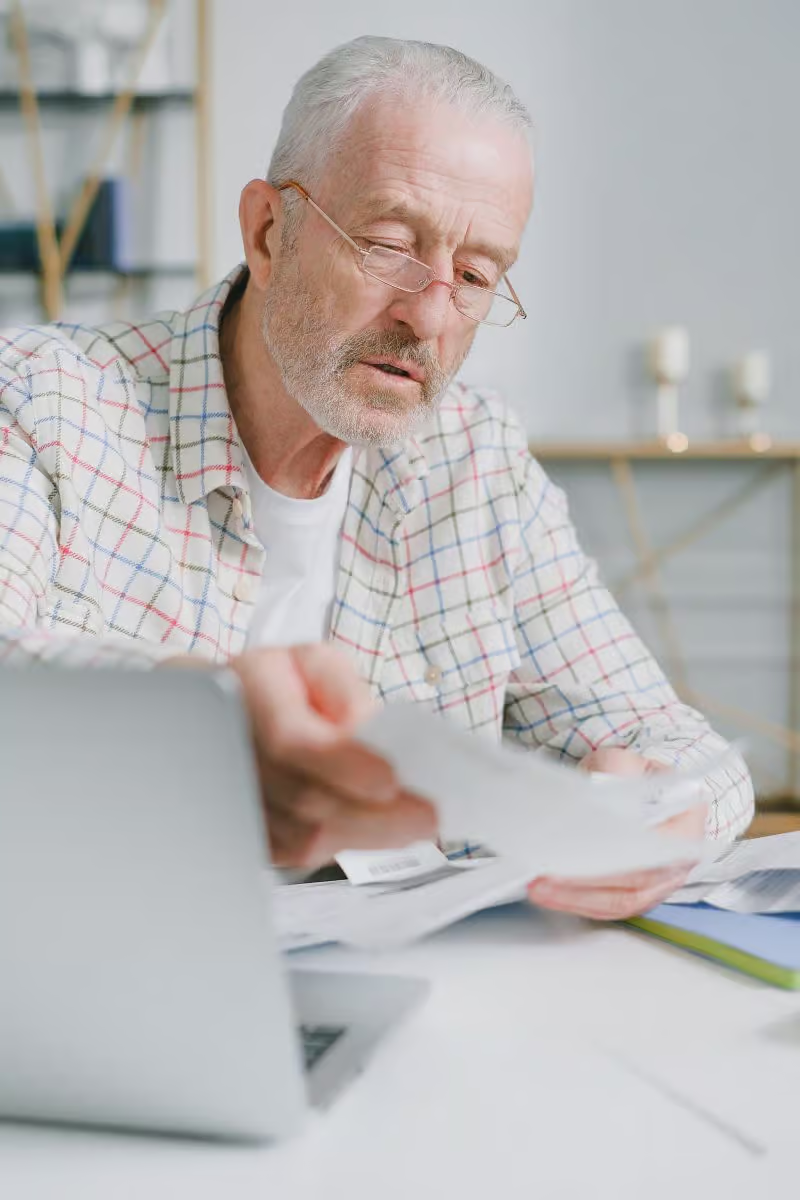
Recent adjustments to bank checking account policies have raised concerns, especially among households grappling with increased living costs. Some financial institutions are raising the minimum balances required to avoid monthly maintenance fees, a shift that could add financial strain to retirees and others living paycheck to paycheck.
TD Bank Raises Minimum Balance Requirement
TD Bank recently announced an increase in the minimum daily balance needed for its Convenience Checking account, raising the threshold from $100 to $250 as of January 4, 2026. Should customers fail to maintain this balance, they risk incurring a $15 monthly maintenance fee, which can accumulate to $180 annually. This shift may catch many customers off guard, particularly those who have long relied on their banking arrangements without scrutiny.
Understanding the Impact of Minimum Balance Requirements
While minimum balance requirements may seem trivial, they can significantly affect those who need to maximize every dollar. According to a 2023 National Survey of Unbanked and Underbanked Households by the Federal Deposit Insurance Corporation, 42.3% of unbanked households cited insufficient funds to meet minimum balance requirements as a barrier to banking services. For many, avoiding unnecessary charges can dramatically improve their budgetary situation.
Complex Fee Waiver Structures at Other Banks
Different banks implement varying rules regarding maintenance fees. For example, Chase’s Total Checking account imposes a $15 monthly fee, which customers can avoid by meeting specific criteria, such as maintaining a balance of $1,500 or making qualifying electronic deposits of at least $500 per statement period. Consumers need to understand these requirements thoroughly in order to manage their finances effectively.
Reasons Behind Monthly Maintenance Fees
Banks generate revenue not just through interest on loans and transaction fees, but also through maintenance fees. While some institutions impose these fees based on balance or deposit requirements, others may waive them under specific conditions. Customers need to evaluate whether their checking accounts offer sufficient benefits to justify any ongoing fees.
Considerations for Social Security Recipients
For retirees relying on Social Security, checking account fees can chip away at necessary funds for daily expenses. For instance, a monthly $15 fee translates to an annual cost of $180, which could be better allocated for essentials like groceries or utilities. To avoid these additional costs, retirees should inquire whether their accounts qualify for fee waivers based on direct deposits, including benefits.
Opportunity Costs of Maintaining High Balances
While keeping a higher balance in checking accounts might alleviate maintenance fees, it often comes at the cost of missed interest earnings. For instance, TD Bank’s Convenience Checking account does not yield interest, potentially leading customers to forfeit gains that could be accrued in a savings account. Evaluating the trade-offs between maintaining the required balance and moving funds into an interest-earning option is crucial for financial health.
Exploring Alternatives without Maintenance Fees
Consumers in search of alternatives can find checking accounts that do not require minimum balances or maintenance fees from various online banks, community banks, and credit unions. The FDIC’s BankFind tool is a useful resource for confirming a bank’s federal insurance status, while the National Credit Union Administration can assist in identifying insured credit unions. It’s essential to compare various features, including fees and access, before committing to a new account.
Recourse for Unexpected Fees
If a maintenance fee arises unexpectedly, reviewing the current fee schedule and recent statements can clarify the issue. Contacting your bank may yield opportunities for a courtesy refund, particularly for first-time expenses or legitimate misunderstandings regarding account changes. If you believe inappropriate fees have been assessed, consider submitting a complaint to the Consumer Financial Protection Bureau.
Final Thoughts on Avoiding Fees
Recent policy changes at banks can introduce unforeseen expenses for long-time customers. The modification of TD Bank’s minimum balance demonstrates how quickly a small change can significantly impact account fees. Navigating these banking intricacies and exploring qualified alternatives or incentives can help retain your hard-earned savings. Ensuring that your checking account meets your needs without incurring unnecessary charges is pivotal for effective financial management.
Have you faced increased minimum balance requirements or monthly fees from your bank? Share your experiences in the comments.
Similar Articles You May Find Interesting
Treasury Modernization: Transforming Banking Operations for the Digital Era
Banks Are Reintroducing Maintenance Fees on Low-Balance Accounts
7 Forbidden Credit Card Fees Banks Try to Sneak Through
Most Americans Don’t Realize Their Bank Tracks Spending Categories
7 Personal Data Leaks That Could Hit Your Bank Account Next
Teri Monroe began her career in communications with local government and nonprofit sectors. Today, she writes freelance articles on finance and lifestyle topics while managing her own small business. In her spare time, she enjoys golfing, taking long walks with her dog, and playing pickleball.

Chief Editor of Quincy City Beat — Quincy, MA's independent investigative newspaper covering Greater Boston and the entire Commonwealth of Massachusetts with fearless public accountability and free access for all readers.



Discussion about this post