

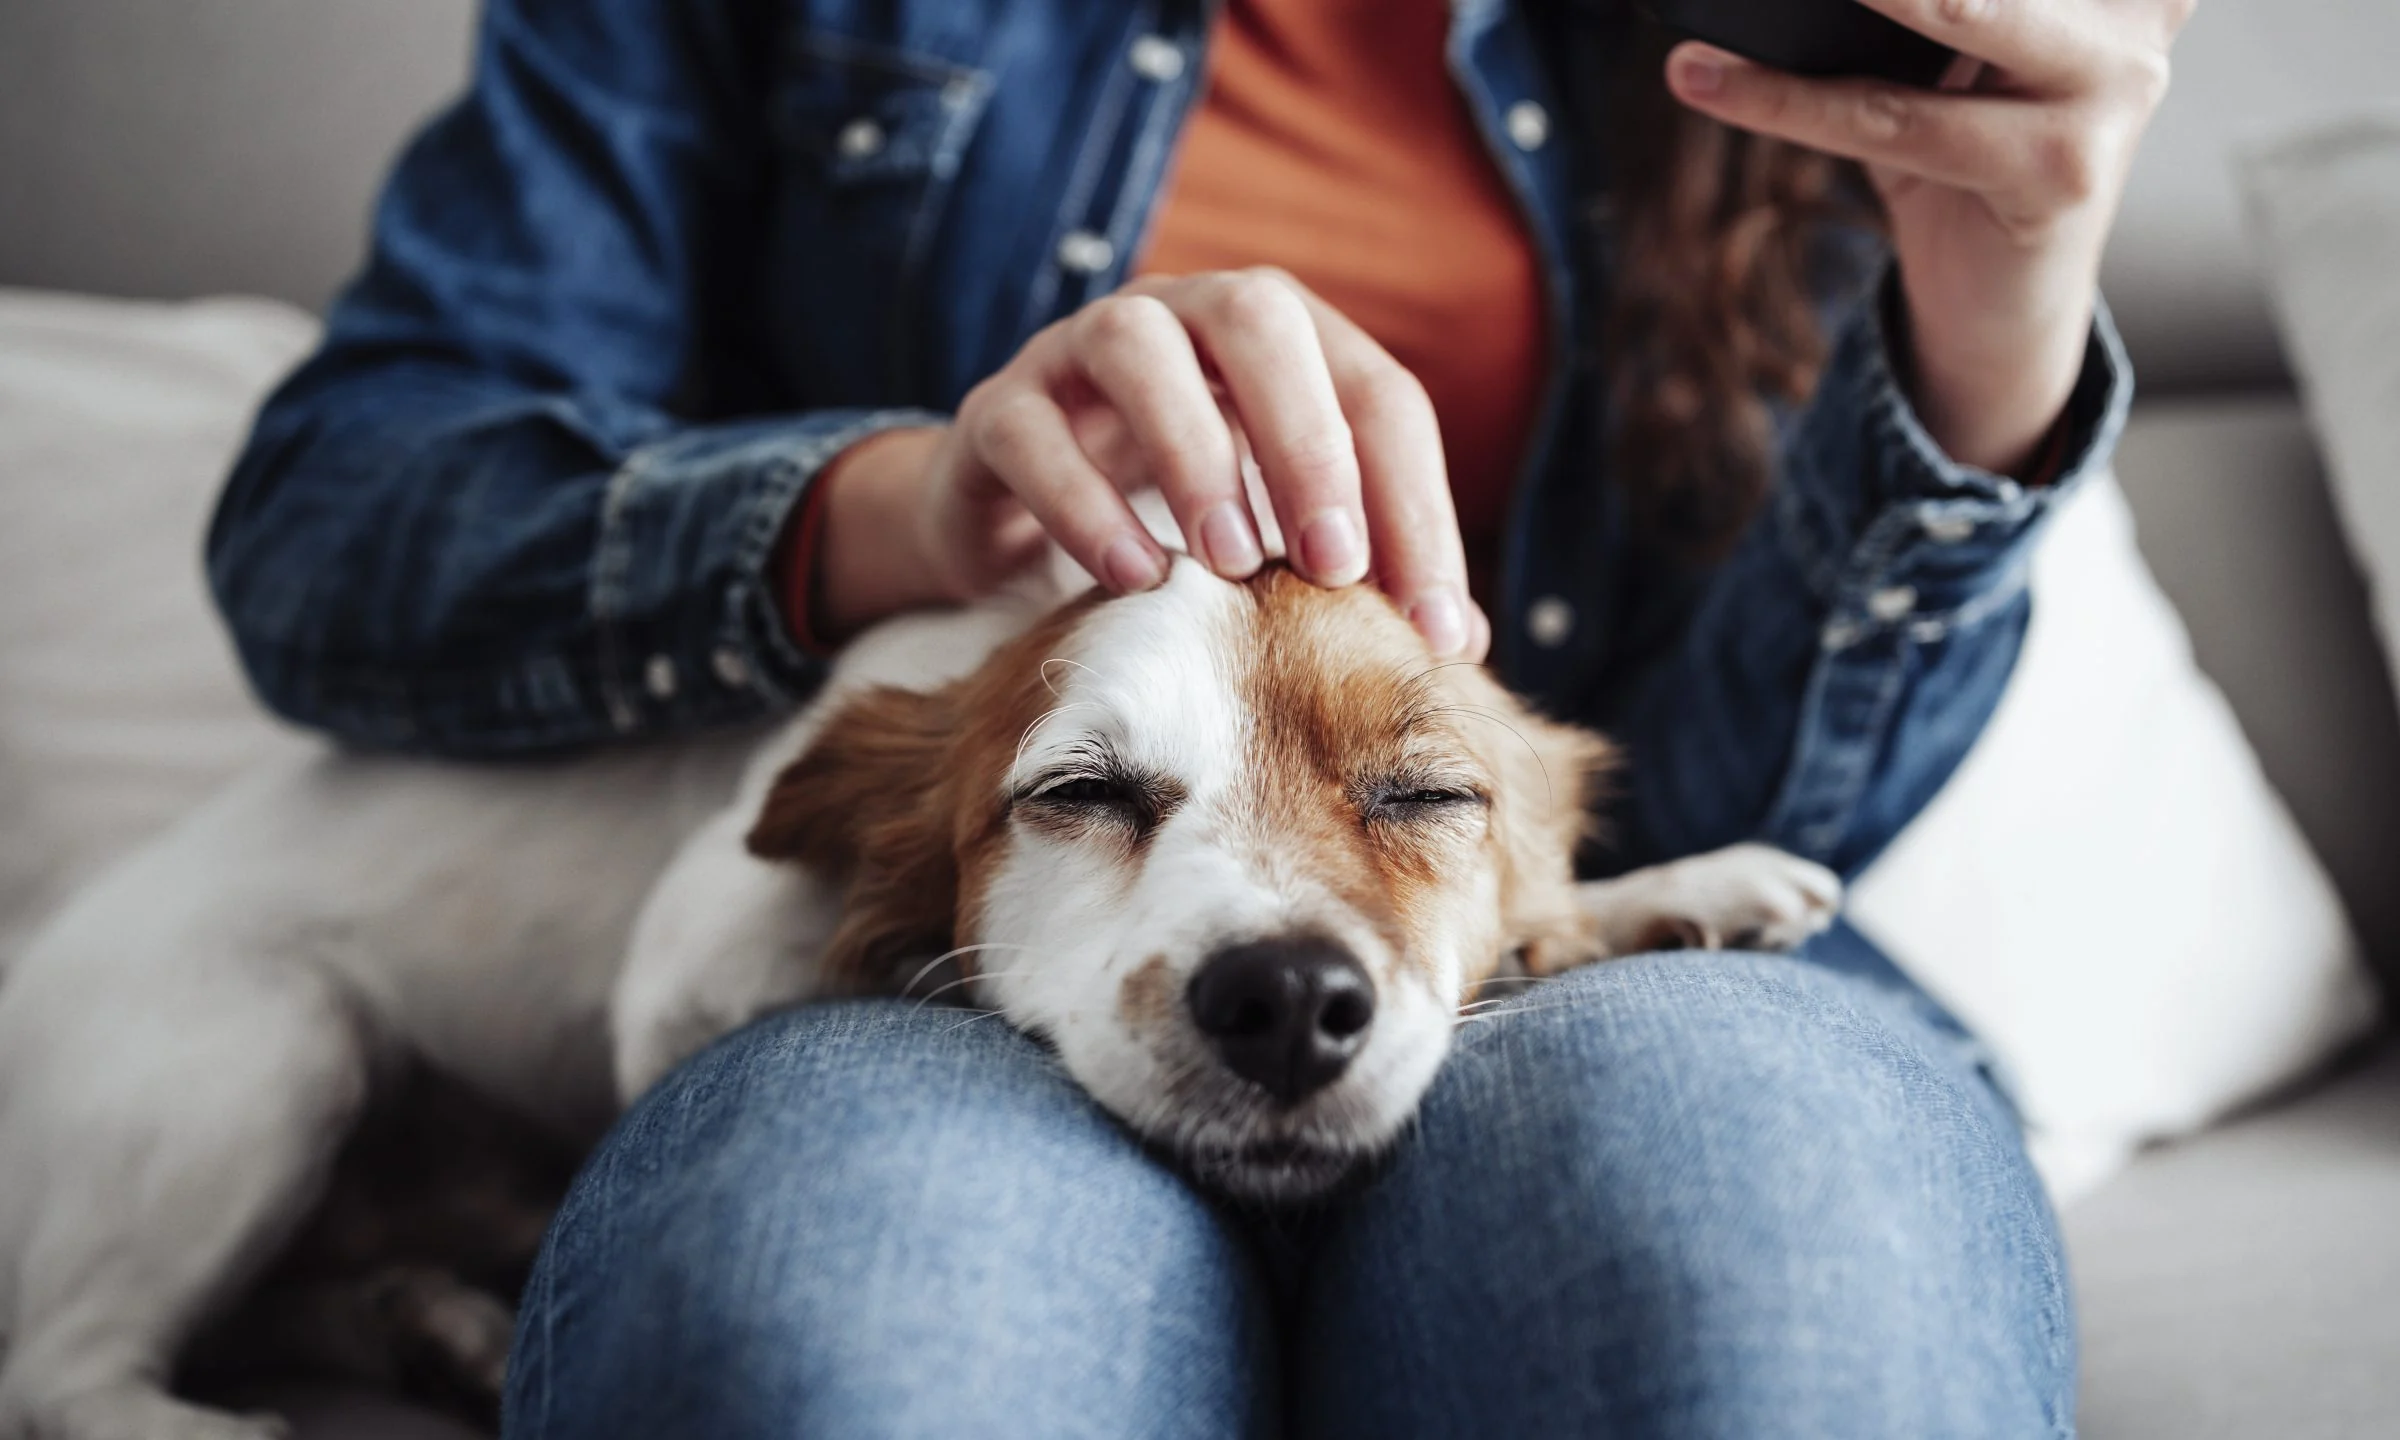
The Importance of Pet Insurance in Safeguarding Your Animal’s Health
Ensuring the well-being of pets through insurance is increasingly viewed as essential, akin to acquiring health coverage for family members. With pets being integral parts of the family unit, many owners are considering insurance options to protect their beloved companions.
Understanding Pre-existing Conditions in Pet Insurance
Potential pet insurance shoppers may find the associated costs daunting, often reaching into the hundreds annually. For myriad pet owners, the decision to invest in such coverage, regardless of their pet’s current health, is informed by the implications surrounding pre-existing conditions.
A pre-existing condition is defined as any illness or injury that presents symptoms prior to the initiation of an insurance policy. Commonly, pet insurance companies exclude these conditions from coverage.
Dr. Rebecca Greenstein, chief veterinarian at Kleinburg Veterinary Hospital, highlights a growing trend in claim denials tied to pre-existing conditions. “The essence of insurance lies in providing extensive coverage for various needs,” she explains. “However, if significant medical issues are excluded, you might be paying premiums without the assurance of support when claims arise.”
For prospective pet insurance buyers, initiating coverage before any health issues manifest is advisable.
Implications of Pre-existing Conditions on Future Coverage
The presence of a pet’s pre-existing conditions can shape future insurance coverage, determining the range of treatments available down the line.
For instance, if a dog showcases allergy symptoms before a policy is secured, insurers are unlikely to cover related treatments, such as allergy shots. This limitation can extend to secondary issues, such as skin irritations or ear infections, as noted by Dr. Michael Goldstein from Billerica Veterinary Hospital.
A specific scenario illustrates the impact of timing: a dog treated for a hot spot one year and then for an ear infection later may face a denied claim if insurance was purchased after the initial vet visit. Given the connection between these ailments and underlying allergies, exclusions may apply. To navigate these complexities, obtaining insurance when pets are young and symptom-free is an optimal approach.
Risks of Foregoing Pet Insurance
Evaluating the financial benefits of pet insurance can be complex. Accident and illness coverage plans, which are the most prevalent, average $836 per year for dogs and $435 for cats, based on data from the North American Pet Health Insurance Association (NAPHIA). Owners could go several years paying these premiums before facing an unexpected veterinary crisis or chronic health issue.
It isn’t feasible to predict whether a pet will maintain good health or incur significant medical expenses. However, examining prevalent chronic conditions that emerge as pets age can clarify the potential value of insurance. Specifically, cats over ten have a 40% incidence rate of chronic kidney disease, with annual treatment costs possibly surpassing $1,200.
Moreover, skin allergies like atopic dermatitis affect roughly 15% of dogs, with initial vet visits for such issues costing $250 or more. Chronic conditions can lead to cumulative expenses throughout a pet’s life, especially if surgical interventions, such as those related to hip dysplasia, are required. While many policies cover surgical costs as long as conditions aren’t pre-existing, waiting periods for orthopedic issues highlight the need for timely coverage.
The fundamental advantage of having pet insurance is the ability to prioritize the best treatment options without being limited by financial constraints. Dr. Greenstein emphasizes, “It’s heartbreaking when critical treatment decisions come down to financial limitations.”
Exploring Alternatives to Traditional Pet Insurance
For pet owners who find standard insurance coverage cost-prohibitive, accident-only plans offer a more economical alternative, averaging $190 annually for dogs and $112 for cats, according to NAPHIA. These plans provide coverage for injuries resulting from accidents but will not address the prevalent health issues that lead to the majority of insurance claims, as indicated by the insurer Lemonade.
In fact, over 60% of claims submitted by Lemonade stemmed from illnesses in the past year, significantly overshadowing claims related to preventive care. Similar trends have been observed at Nationwide, where chronic health issues constitute the majority of insurance claims.
Regardless of the insurance route chosen, it is wise to establish a savings fund specifically for potential pet emergencies and illnesses. Creating such a financial cushion ensures that treatment decisions are not skewed by immediate cost concerns.

Chief Editor of Quincy City Beat — Quincy, MA's independent investigative newspaper covering Greater Boston and the entire Commonwealth of Massachusetts with fearless public accountability and free access for all readers.



Discussion about this post